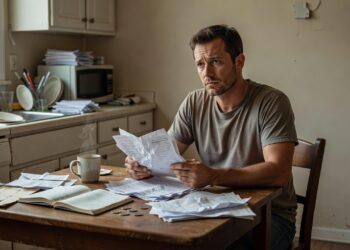
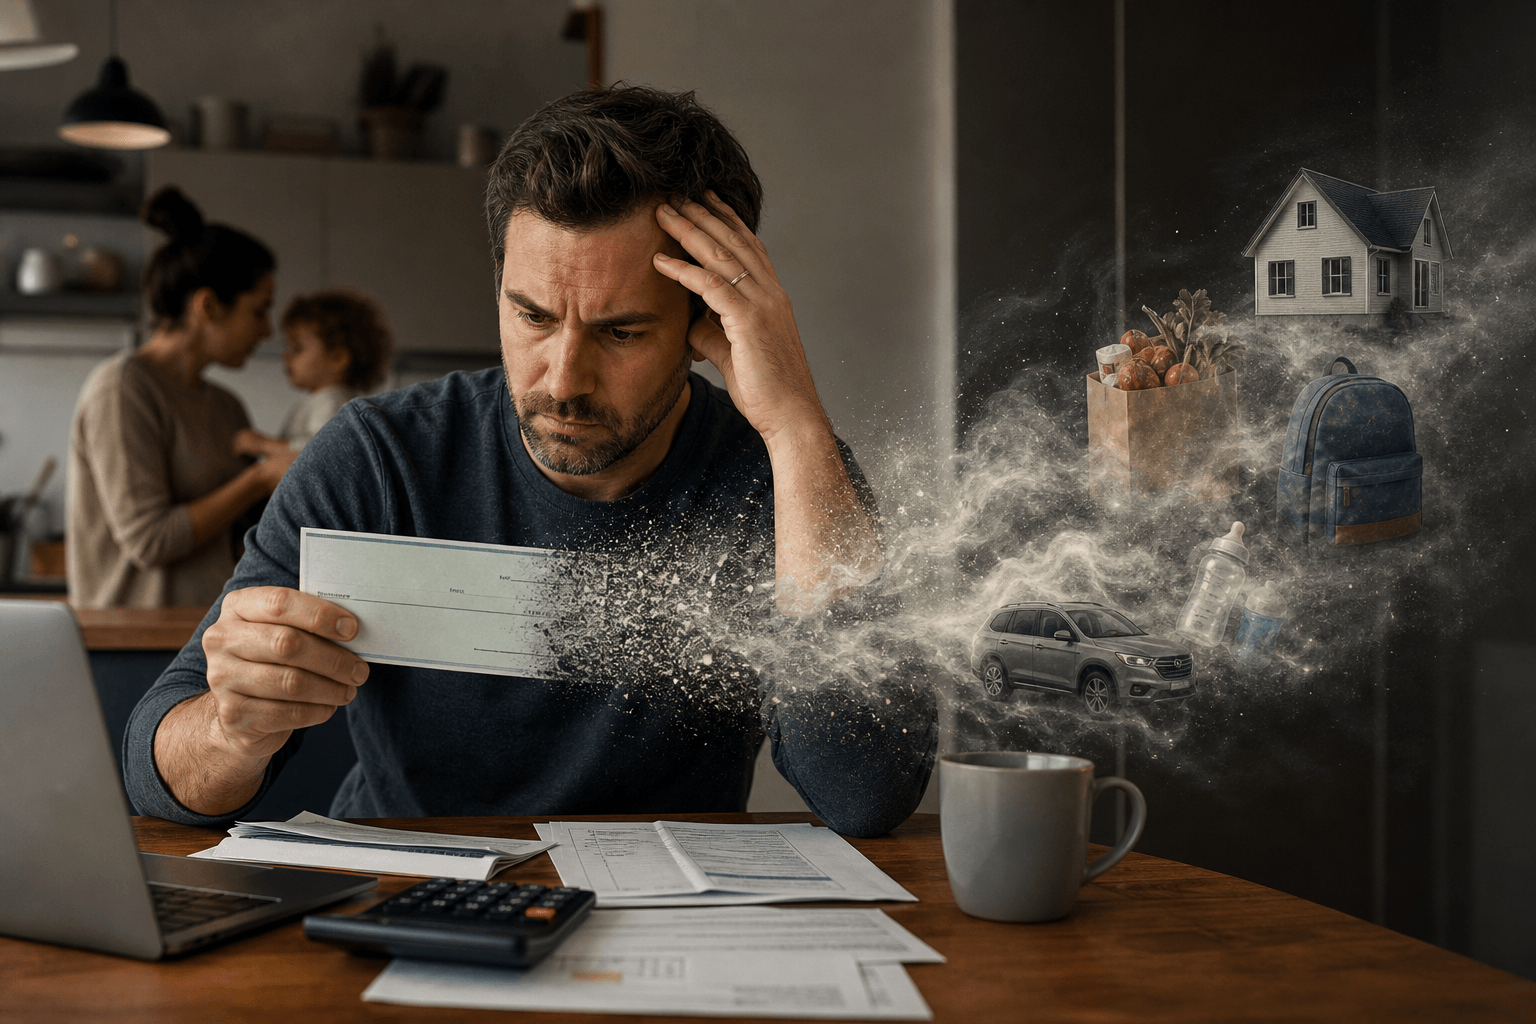
For many working fathers, the problem is not that income is too small to notice. It is that the money seems to get assigned the moment it lands. The paycheck arrives, and almost before it feels like income, it has already turned into housing, food, childcare, transportation, school costs, savings transfers, and a long list of small obligations that never look large on their own. That is why the feeling is often not panic, but speed: money disappears because family life creates a very fast sequence of decisions.
The paycheck gets claimed before it feels like spending money
A working father’s income often does not disappear in one dramatic purchase. It disappears through a chain of normal obligations that start immediately after payday. In households with children, money is routinely expected to cover not only current bills but also future needs, from development and schooling to everyday care and stability. One report on parenthood and demographics noted the difficult expectation that parents will invest huge amounts of time and money in children’s development, which helps explain why income can feel spoken for before it is ever mentally available.
That matters because money behavior is partly about timing. If most of your paycheck is already mentally reserved for rent, groceries, childcare, or debt payments, the remaining balance is small enough to vanish quickly through ordinary purchases. The feeling of disappearance is often not a sign of carelessness; it is a sign that the household budget has very little slack.
Family costs are spread out, not centralized
One reason income feels hard to hold onto is that family spending is fragmented. Instead of one obvious monthly bill, you have many smaller categories that arrive at different times: gas, lunches, clothing, activity fees, repairs, co-pays, gifts, subscriptions, school supplies, and the inevitable replacement item you did not plan on. None of these feels large enough to be a crisis, but together they create a constant drain.
That fragmentation makes it hard to answer a simple question: “Where did the money go?” The answer is usually that it went to several perfectly reasonable places, each of which looked manageable in isolation. A father may not feel he made a single expensive mistake. He may feel that the family system itself is expensive to operate.
The practical issue is not just spending, but tracking. When expenses are spread across different days and categories, the brain tends to underestimate how much has already been committed. A paycheck can seem bigger in the morning than it does by the end of the week because the costs are no longer visible as one number.
The mental load of earning and coordinating at the same time
Working fathers are often managing more than the job itself. They are also coordinating schedules, pickups, repairs, school communication, and the quiet operational work that keeps a family moving. That coordination has financial consequences because it pushes spending into response mode. When something breaks, needs replacing, or must be paid quickly, there is rarely time to compare options calmly.
This is where money behavior gets tricky. Fast decisions are expensive decisions. A rushed day can lead to more takeout, more convenience purchases, or a more expensive service choice simply because the family cannot wait. Over time, those choices can make income feel thinner than expected.
The research on parenting stress and employment also points to a related pattern: workplace inflexibility is associated with more parenting stress, and that association can be especially strong for fathers in some contexts. In plain language, when work is rigid and home demands are non-negotiable, money management becomes harder because time pressure increases the odds of reactive spending.
Child-related spending is emotionally nonnegotiable
Many expenses that hit working fathers are not luxuries in their own minds. They are identity expenses: the things that feel necessary to be a good provider, a present parent, or a stable adult in the household. That is why cuts in this area often feel different from ordinary budget trims. It is one thing to reduce a hobby budget; it is another to say no to a kid’s clothing, activity, or birthday expense.
This emotional structure matters. When spending is tied to care, protection, or competence, people are less likely to question it in the moment. They may even see restraint as a failure. That can produce a strange pattern: a father wants to be disciplined with money, but the categories he would need to cut are the same categories that feel morally charged.
The result is not necessarily overspending in the classic sense. It is often a budget that has very few permission points for saying, “Not this time.” Without those boundaries, the household default becomes yes, and yes is expensive.
Income can rise while financial breathing room stays flat
A lot of people assume a higher income should automatically feel better. But income and freedom are not the same thing. If your pay increases while family obligations increase at the same time, the emotional experience may not improve much. In fact, it can worsen if the new income disappears into higher childcare, housing, transportation, or child-centered spending.
This is one reason fathers sometimes feel that progress never shows up. They work harder, earn more, and still feel one expense away from friction. That is not because the extra income is imaginary. It is because the extra income has been absorbed by a more demanding cost structure.
A useful way to think about this is to separate gross income from discretionary space. Gross income tells you what came in. Discretionary space tells you what is actually available after the family system takes its share. For many working fathers, the second number is the one that matters emotionally.
A simple way to see whether the money is actually disappearing
If income feels like it vanishes instantly, do a quick three-part check for one month.
First, list the money that is committed before payday even arrives. This includes automatic transfers, bill payments, debt payments, and any regular child-related expenses you know will happen. These are not surprises; they are pre-decisions.
Second, separate true surprises from predictable irregular costs. A tire replacement is not monthly, but it is predictable enough to plan for. School events, clothing replacement, holiday spending, and seasonal fees often behave the same way. If they keep showing up and still count as surprises, they will always make income look smaller than it is.
Third, compare what remains after those commitments to what you emotionally thought was left. That gap is the key behavioral clue. If the number is smaller than you expected, the issue may not be a spending problem so much as a visibility problem.
Build a buffer for the life that keeps interrupting the budget
The best response is usually not a harsh spending crackdown. It is a better structure for a life with interruptions. Working fathers often need a budget that assumes the household will be interrupted regularly, because it will be.
That means building a small buffer category for the kinds of costs that do not feel monthly but show up every month in practice. It can also mean giving family spending its own line items instead of leaving everything in a vague general fund. The more specific the budget, the less money has to be mentally “re-found” later.
It also helps to give one job to each dollar before the paycheck arrives. When income is assigned in advance, the feeling of disappearance becomes less mysterious. You may still not have much left, but at least you know why.
For some households, the practical win is not increasing income right away. It is reducing the number of moments when the budget has to be rescued by improvisation. Fewer rescues usually mean less leakage.
The question that cuts through the frustration
When a working father says his income disappears instantly, the useful question is not “Why can’t I get ahead?” It is “How much of this paycheck is already committed to family life before I can even use it?” That shift matters because it turns a vague sense of failure into something measurable.
If the answer is “most of it,” the problem may be structural: the household cost base is too high for the current income, or too many expenses are landing outside the budget. If the answer is “less than I thought,” then the next step is better tracking and categorization, not self-blame.
Either way, the feeling has a logic. Working fathers are often not watching money vanish into nonsense. They are watching it get absorbed by a demanding, emotionally important life, one ordinary expense at a time. Once you see that pattern clearly, it becomes easier to decide what is truly fixed, what can be planned, and what deserves a boundary.
Related Reading
- Why Working Fathers Feel Like Income Disappears Fast
- Why Men Over 50 Fear Outliving Their Income
- Why Men Over 50 Fear Outliving Their Income
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of where your income goes each month, try the Salary Breakdown Calculator.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.