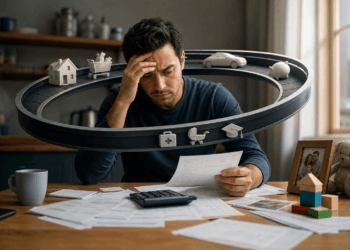
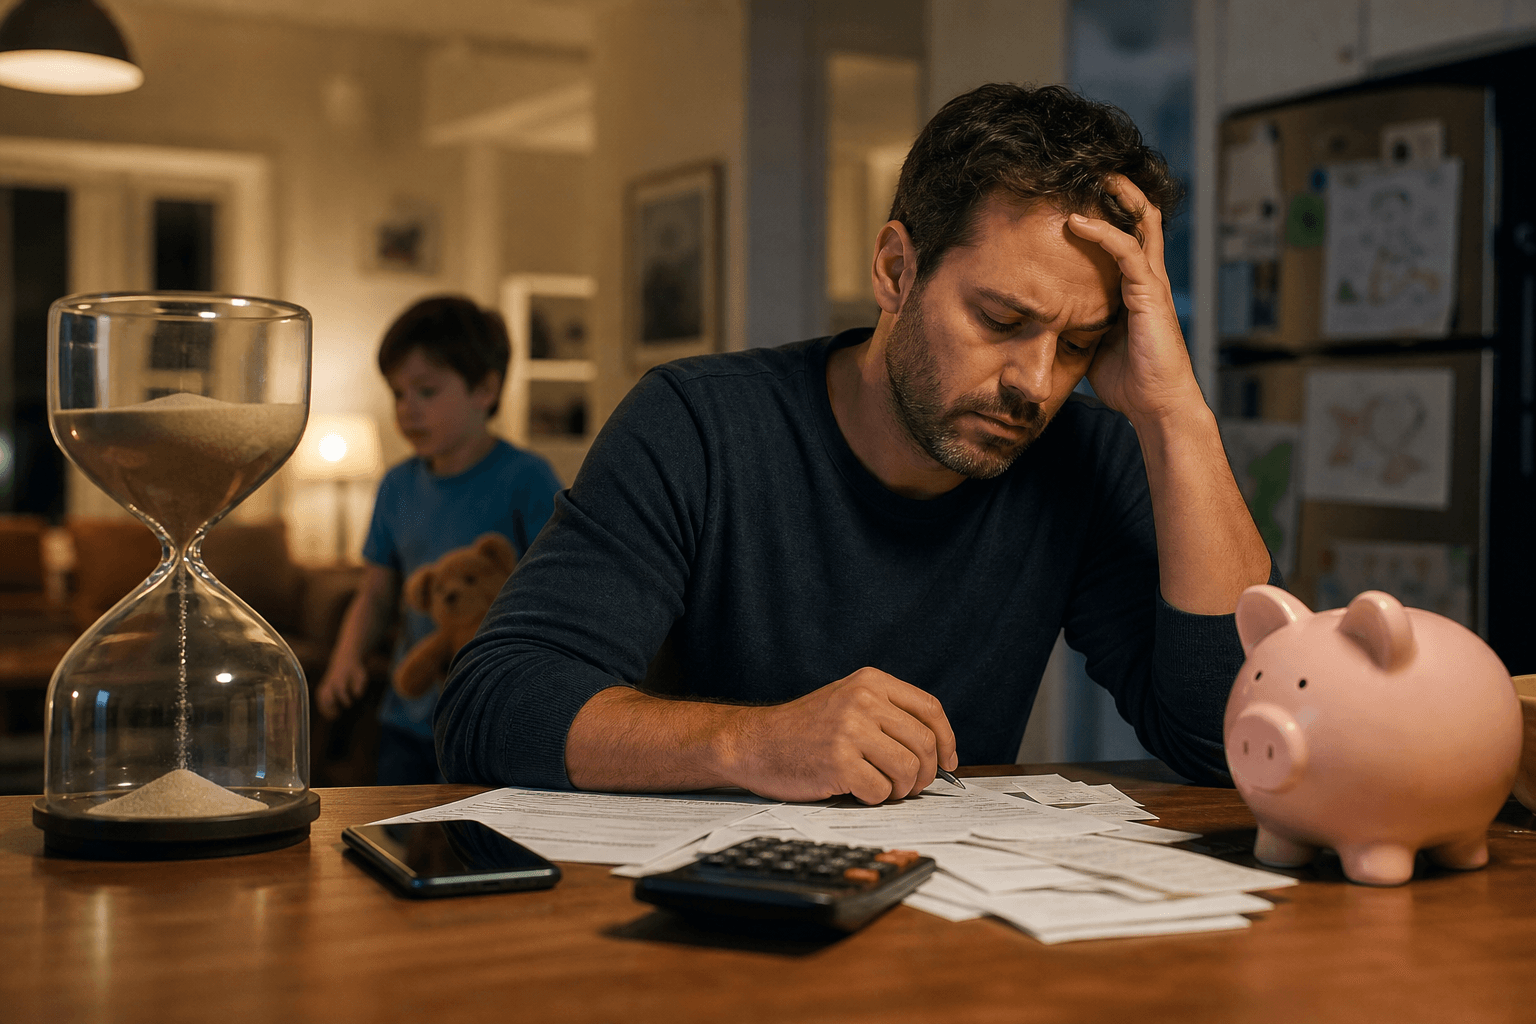
For many working fathers, money stress is not one big crisis. It is the steady sense that the next bill, school expense, repair, or work conflict is always waiting in the wings. Even when income is stable, the mind does not get to stand down. Research on parents shows why: financial pressure, child-related emergencies, and work-life strain often overlap instead of arriving one at a time. That overlap is what makes financial rest feel impossible.
The problem is not only the budget
When fathers say they never feel financially rested, they are usually describing more than a balance sheet. They are describing alertness. A budget can be technically fine while the person managing it still feels one surprise away from trouble.
That matters because money fatigue is often built from repeated small decisions: whether to work late, whether to replace something now or later, whether to absorb a cost or ask for help, whether to miss time with family to protect income. Each choice may be rational on its own. Together, they create a life that feels permanently on-call.
Why the pressure keeps reappearing
Working fathers tend to live inside a loop of recurring obligations. Paychecks arrive on schedule, but expenses do not. Childcare, food, housing, and transportation costs keep moving, and family needs do not wait for a convenient month.
Research from Pew found that one in four U.S. parents struggled to afford food or housing in the past year. That is not a niche problem; it is a sign that a lot of families are operating close to the edge. Pew also found that 19% of parents who work at least part time said they would be extremely or very worried about losing pay if they had to take a day or two off because of child care issues. In other words, even brief disruptions can feel expensive before they happen.
That is the key pattern: fathers are not just paying bills. They are mentally pricing interruptions.
The invisible cost of being the fallback person
Many working fathers become the default backup plan. If a child is sick, if a school event runs long, if a partner needs support, if the car breaks down, someone has to decide what gets delayed and what gets paid for. That role is financially draining because it requires constant readiness.
This is where “rest” starts to disappear. Rest usually depends on the feeling that the system can coast for a while. But when you are the fallback person, the system never quite coasts. You may not be in an emergency, but you are always prepared for one.
That readiness has a cost even when no money is spent. The mind keeps track of risk: lost wages, missed work, a childcare gap, a household repair, or an unexpected medical or family issue. The result is a form of financial vigilance that can feel endless.
Work-life friction turns into money friction
Fathers in transition to parenthood have described work-life balance and financial issues as major stressors, along with concerns about the health of their partner and baby. Those pressures do not live in separate boxes. They overlap.
A late meeting can become a childcare fee. A sick day can become lost pay. A work schedule that looks manageable on paper can become expensive in practice if it leaves no room for the family’s needs. Over time, this turns time pressure into money pressure.
That is why financial rest is not only about earning more. It is also about whether work gives enough flexibility for life to happen without penalty. When the answer is no, every ordinary family interruption starts to feel like a financial threat.
Why “doing everything right” still feels exhausting
Some fathers try to solve the problem by tightening every category. They track spending, cut extras, avoid debt, and work harder. Those actions can help, but they do not always produce relief.
Why? Because the stress often comes from uncertainty, not just excess spending. If you can cover this month but you are not confident about the next disruption, your nervous system does not fully stand down. You may keep enough money in motion to stay solvent, but never enough margin to feel settled.
This is also why income alone does not always fix the feeling. A larger paycheck can reduce strain, but if new income is immediately absorbed by housing, childcare, commuting, debt service, or constant household repairs, the sense of rest still does not arrive. Money may be flowing more smoothly while the person still feels exposed.
A simple way to tell whether the stress is about margin or momentum
It helps to ask a practical question: if one ordinary family disruption happened this week, would it create a money problem or merely an inconvenience?
If the answer is “money problem,” then the issue is margin. There is not enough room between income and obligations.
If the answer is “inconvenience,” but the stress still feels intense, then the issue may be momentum. The household might technically be stable, but the father is carrying too many simultaneous roles: earner, planner, problem-solver, backup caregiver, and risk manager.
A useful diagnostic is to write down the three events most likely to throw the month off track. For many fathers, those events are not dramatic. They are things like:
– a child care gap
– a missed shift or unpaid hour
– an unexpected household repair
– a school expense
– a transportation problem
If those are the triggers, the real question is not “How do I become perfectly prepared?” It is “Which of these disruptions can I absorb, and which ones need a plan before they happen?”
The relief comes from fewer points of failure, not perfect control
Financial rest rarely comes from total control. It comes from reducing the number of places where one problem can cascade into five others.
That can mean keeping a small cash buffer for the expenses that show up without warning. It can mean separating irregular family costs from everyday spending so they do not ambush the monthly budget. It can mean checking whether a work schedule, commute, or side income is creating more strain than it solves. And it can mean having an honest household conversation about which risks are shared and which are silently being carried by one person.
For some families, even a modest buffer changes the emotional math. A fund that covers a day or two off work, a childcare hiccup, or a small repair may not feel dramatic, but it can interrupt the chain reaction that turns a routine problem into a crisis.
A steadier money routine for fathers who never feel caught up
A better goal than “feeling financially finished” is building a routine that makes surprises less emotionally expensive.
Start with a short monthly review that answers three questions:
1. What expense surprised us this month?
2. What cost was predictable but irregular?
3. What work or family event would be costly if it happened next month?
Then decide which one of those items deserves a designated plan. Not everything needs a separate account or a perfect system. But the household should know where the pressure points are.
From there, the most useful habit is often not austerity. It is naming the recurring traps: missed pay from time off, school and child-related expenses, transportation, and the subtle creep of “temporary” fixes that become permanent. Once those are visible, they are easier to budget for deliberately instead of emotionally.
Financial rest may never feel complete for a working father, especially during years when family responsibilities are heavy. But it can become more real when the household stops treating every interruption as a surprise and starts treating the known pressures as part of the plan.
Related Reading
- Financial Rest Never Comes for Working Fathers
- Why Fathers Feel Like They Can Never Stop Working
- Why Working Men Feel Like Their Savings Never Grow
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.