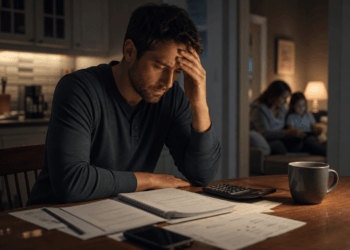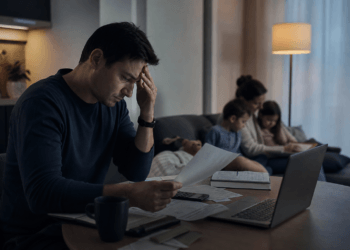
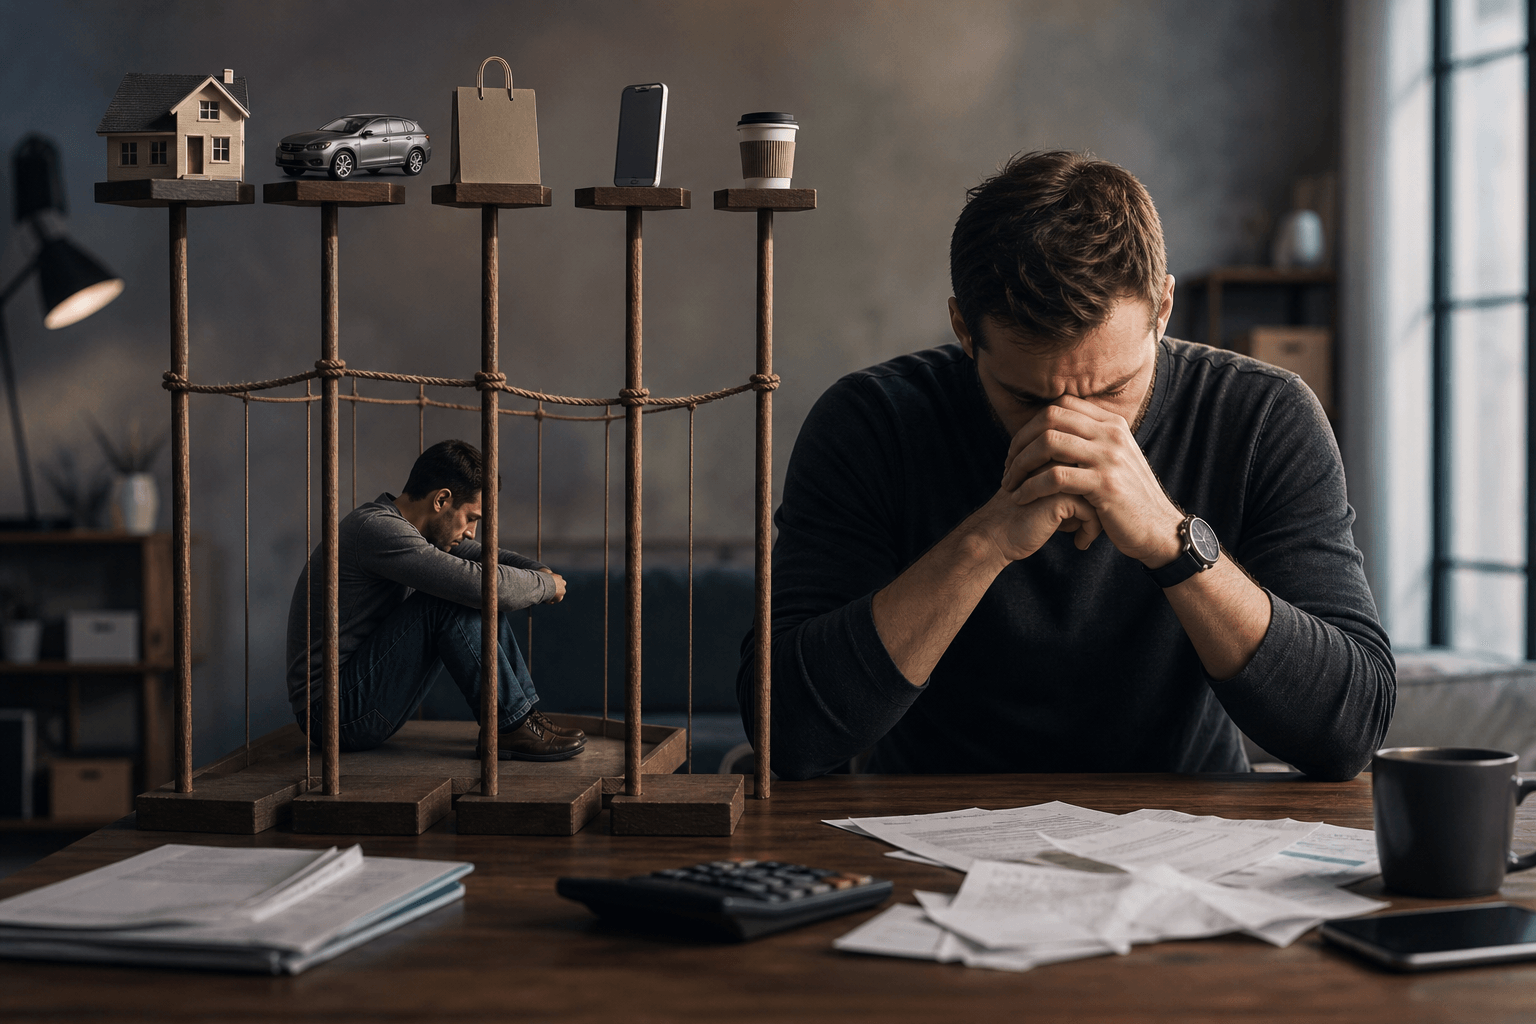
A lot of men do not feel “bad with money” so much as boxed in by the cost of looking stable. The mortgage, the truck, the subscriptions, the meals out, the kids’ expenses, the social pressure to keep up, and the fear of looking like things are slipping can make a decent income feel strangely tight. The result is often quiet frustration: not panic, just the sense that every fixed cost makes freedom smaller. That feeling usually has less to do with one bad purchase than with a lifestyle that became expensive one normal choice at a time.
The trap usually starts with normal choices, not big mistakes
Most lifestyle pressure does not arrive as a dramatic splurge. It builds through choices that seem responsible at the time: a better place to live, a larger vehicle, childcare that makes life workable, dinners out because everyone is busy, and a social calendar that gets harder to ignore. Each decision makes sense on its own.
The problem is that fixed costs are sticky. Once a monthly payment, lease, or routine expense becomes part of life, it is no longer a choice you revisit every week. Men often feel trapped not because they bought something outrageous, but because a collection of reasonable expenses starts behaving like a lock.
That is why the feeling can be hard to explain. On paper, income may look solid. In real life, there is less room to breathe than there used to be.
When “success spending” becomes a silent obligation
A lot of lifestyle cost pressure is social, even when it looks practical. People do not only spend to enjoy themselves; they also spend to signal that life is on track. Housing can be especially powerful here. The neighborhood, the square footage, the commute, the school zone, and the idea of being “settled” all push in the same direction.
Penelope Trunk’s discussion of men with families feeling more trapped points to a familiar pattern: high housing costs, childcare, and the expectation that a higher-income life should also look like a fuller life. In the comments, one example notes that daycare and afterschool care in New York City can run over $20k a year for two children, before evening or weekend babysitting. That kind of number does not just strain a budget; it changes the meaning of every paycheck.
Once a household is organized around a certain image of stability, stepping down can feel like failure even when it would improve flexibility. Men may keep paying for a lifestyle because the alternative looks like loss of status, loss of comfort, or loss of control.
The parts of life that quietly inflate fastest
Some costs are more likely than others to create the feeling of being pinned down. They are not always the largest line items in theory, but they are often the hardest to unwind in practice.
Housing is one. A larger home or a better location can make daily life easier, but it also raises the floor for everything else: furniture, utilities, maintenance, commuting, and expectations about what “normal” now looks like.
Family logistics are another. Childcare, afterschool care, and the constant small purchases around children can turn a flexible budget into a calendar of obligations. Even when both partners are earning, the household can feel less free because more income is pre-committed.
Transportation, too, can become a form of lifestyle drag. A nicer car may feel justified, especially if work or family life is demanding, but car payments, insurance, fuel, and repairs all add weight. Add food delivery, convenience spending, memberships, and “little” monthly charges, and the budget starts to feel crowded before the month is half over.
What makes these costs so difficult is not only the amount. It is the fact that they recur. A one-time purchase hurts once. A recurring expense reminds you every month that your life has become expensive to maintain.
Why men often stay silent about feeling stuck
Many men do not talk about this feeling in plain language. They may describe stress, irritability, pressure at work, or just being tired. But the underlying issue is often a fear of admitting that the life they built is financially heavier than it looks.
That silence has a behavioral side. Men are often socialized to appear steady, capable, and unaffected. The idea of saying, “I feel trapped by my bills,” can sound too close to weakness, even when it is really just a description of the situation. So the feeling gets converted into other behaviors: working longer, avoiding the budget, brushing off new expenses, or telling themselves the pressure is temporary.
HelpGuide notes that financial stress can contribute to depression and anxiety, and that people struggling with debt are more than twice as likely to suffer from depression in one cited study. That does not mean every man under lifestyle pressure is clinically depressed. It does mean money strain can affect mood, concentration, and decision-making in ways that make the trap harder to escape.
Silence also delays the one thing that helps most: a clear look at what is actually consuming the money.
A simple way to see whether your lifestyle has outrun your freedom
If the problem feels vague, use a practical test instead of a moral one. Ask three questions:
1. How much of my monthly income is already committed before the month starts?
2. Which expenses would be hardest to cut for three months if I had to?
3. If my income stayed the same, would this lifestyle still feel acceptable a year from now?
Those questions matter because trapped does not always mean “spending too much.” It often means “too much of my income is locked before I get a chance to choose.”
A useful sign is how much slack remains after necessities and obligations. If the answer is “not much,” the issue may not be lack of discipline. It may be that your current lifestyle leaves no margin for mistakes, downtime, or changes in work.
You can also separate costs into three buckets:
– fixed and hard to change quickly
– flexible but habitual
– optional but emotionally charged
That last category matters more than people think. Some spending is less about utility than about relieving stress, keeping peace, or preserving an identity. If you do not name those motives, you cannot redesign them.
The emotional costs are part of the bill
Lifestyle pressure is not only arithmetic. It can shape how men feel about themselves.
When every choice has financial consequences, decision fatigue grows. A man may start to feel resentful about normal family spending, guilty about wanting anything for himself, or anxious about future expenses that have not even happened yet. Money begins to feel like a series of small traps instead of a tool.
That emotional layer matters because it changes behavior. Some men respond by spending more to feel temporary relief. Others clamp down hard, become controlling, or avoid conversations that would expose the scale of the problem. Both reactions can make the situation worse.
There is also a social comparison effect. If friends, coworkers, or relatives seem to be maintaining a more expensive lifestyle, it is easy to assume everyone else is managing better. In reality, many households are just absorbing the pressure quietly. The appearance of ease often hides a lot of juggling.
Once you see the emotional cost as part of the financial cost, the goal changes. It is no longer just “spend less.” It becomes “build a life that does not require constant mental strain to maintain.”
What gives you room again
The fix is rarely one dramatic move. It is usually a sequence of small reversals that restore choice.
Start by looking for the expenses that create the most commitment for the least real value. A slightly smaller housing cost, one less car payment, fewer recurring services, or a cheaper childcare arrangement can change the shape of a budget more than cutting coffee ever will. The point is not deprivation. It is regaining options.
Next, give every recurring cost a job. Some expenses are worth it because they truly reduce stress, save time, or support family life. Others remain because no one has questioned them in years. When every monthly charge has to justify itself, habits become easier to see.
Then create one visible escape hatch. That could mean building cash reserve space, reducing one fixed expense, or keeping one category intentionally lean. Even a small amount of room changes the feeling of being trapped because it proves your finances are not completely captive to last month’s decisions.
The deeper goal is not to make life small. It is to make life adjustable. Men often feel trapped when their lifestyle is optimized for looking established but not for changing course. Flexibility is what restores calm.
And if the budget already feels heavy, do not wait for a perfect reset. The first win is often simply identifying which parts of the life are optional, which parts are commitments, and which parts are only there because they became the default.
Related Reading
- Why Men Quietly Feel Financially Exhausted by Responsibility
- Why Men Quietly Feel Financially Replaceable at Work
- Why Men Feel Financially Replaceable at Work
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.