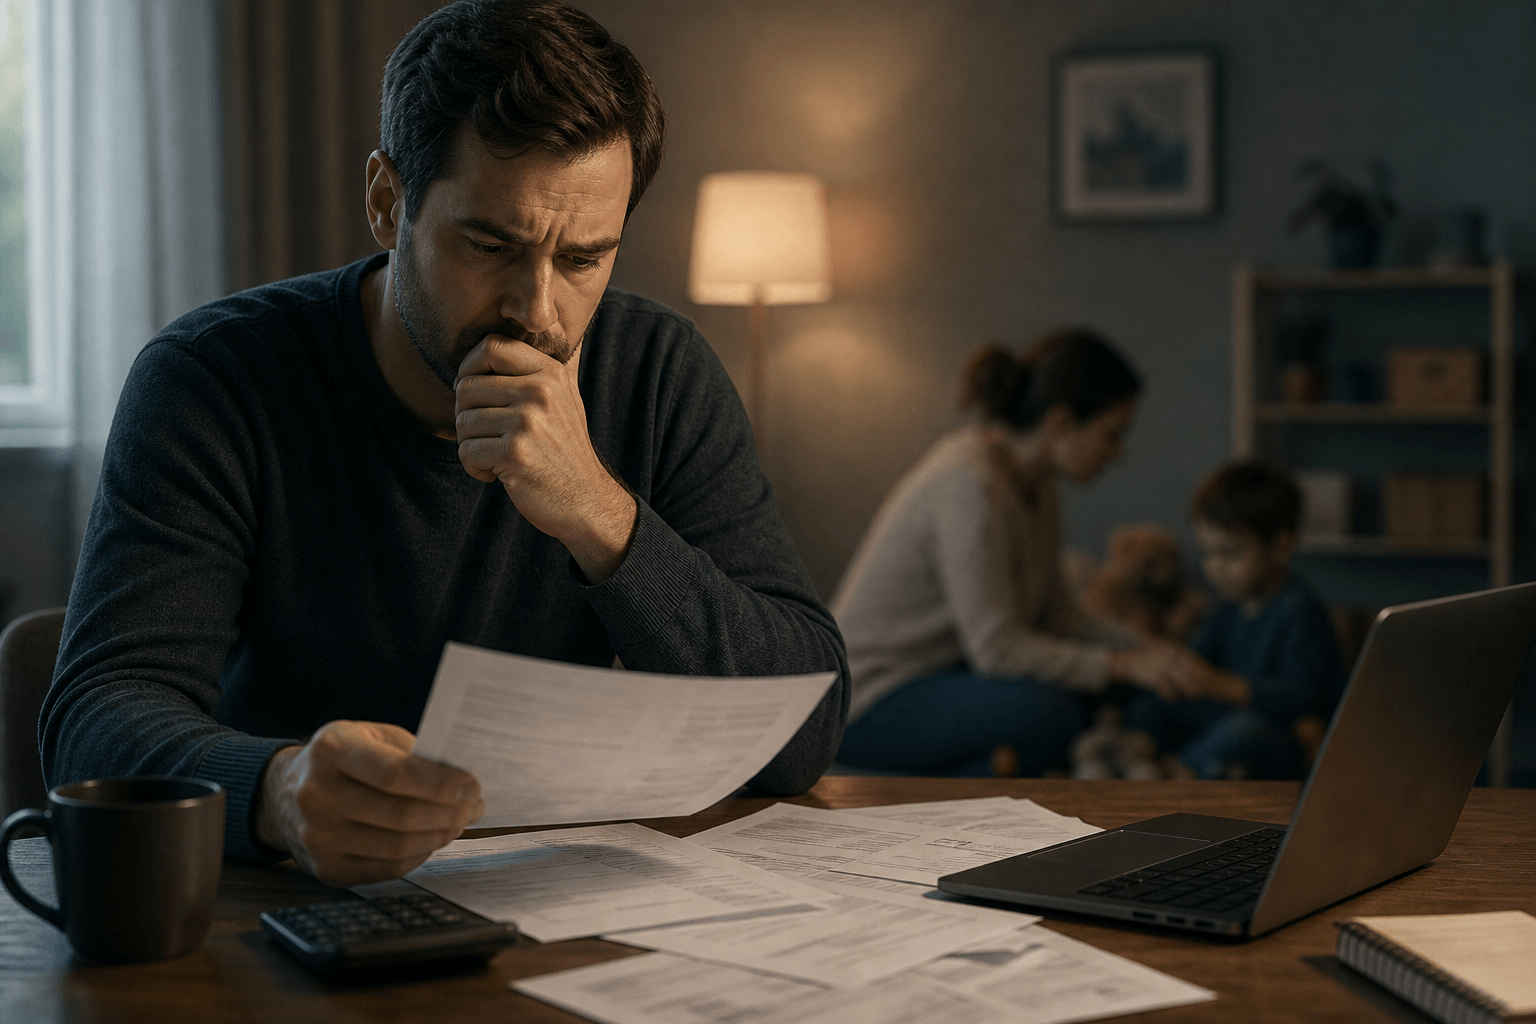
A lot of fathers don’t announce that they are worried about money. They just start making smaller, quieter decisions: driving the old car a little longer, delaying a purchase, saying no to a trip, or taking the safer job path even when it feels limiting. That pattern is not usually about being bad with money. It is often about carrying a constant mental calculation in the background: What if this choice makes things harder for my family later? Once that worry becomes part of everyday decision-making, money stops being one category of life and starts coloring all of it.
The pressure to provide turns money into a constant test
For many fathers, money is not experienced as a neutral tool. It becomes tied to identity, competence, and the sense of whether they are holding up their end of the family bargain. CHKD notes that even when finances are stable, men can feel pressure to pursue money in order to demonstrate masculinity, and they may judge their role as a father by how much they can provide financially.
That matters because a father who sees every expense as a measure of responsibility will rarely make decisions only on the basis of price. He will weigh whether the choice makes him look careless, weak, unprepared, or selfish. A dinner out, a sports fee, a car repair, or a change in work hours can feel larger than the dollar amount attached to it.
In practice, this can create a kind of mental inflation. The cost of the decision is not just the cost in dollars; it is the imagined cost to status, security, and family stability. That is why money worry can appear in decisions that seem unrelated to money on the surface.
Everyday choices get filtered through a worst-case scenario
When financial worry is always active, the brain starts stress-testing ordinary decisions. Instead of asking, “Can we afford this?” the question becomes, “What happens if something else goes wrong right after this?” That shift makes even modest choices feel risky.
A father might keep an aging car longer than he should because a replacement feels too exposed. He might avoid booking a vacation because one unexpected bill could make the month feel off-balance. He might accept that a house repair can wait, not because he is indifferent, but because he is mentally reserving cash for the next unknown.
This is one reason money worry can be so hard to spot from the outside. The behavior may look like caution, frugality, or practicality. But underneath, the decision is often being made in a state of anticipation: a belief that another demand is always about to arrive.
Small spending choices can become moral choices
Once financial anxiety gets tied to being a “good father,” ordinary purchases can take on moral weight. A father may not just think, “This is expensive.” He may think, “If I buy this, I am not being responsible.” That moral framing can make spending feel emotionally dangerous even when the household budget can absorb it.
This is where many people get stuck in a loop. They may know, logically, that the family needs enjoyment, convenience, or rest. But emotionally, spending can feel like a failure to protect. The result is often overthinking, hesitation, or guilt after even routine purchases.
The problem is not only that this can make life less enjoyable. It can also distort judgment. When guilt enters the decision before the numbers do, the family may end up under-spending on things that would genuinely improve day-to-day life, such as childcare help, preventive maintenance, or a purchase that saves time and stress.
Money worry often shows up as over-control, not panic
Some people assume financial anxiety looks obvious: visible stress, obvious panic, or frequent arguments about bills. But for many fathers, the more common expression is controlled, restrained behavior. The worry gets converted into management.
That can look like checking accounts too often, mentally rehearsing what would happen if income dropped, refusing to make flexible plans, or becoming unusually protective of savings. It can also look like a preference for predictability over opportunity. A person may choose the lower-paying, more stable path because uncertainty itself feels too expensive.
This is not irrational. Financial strain is real, and the research on household financial stress shows that many adults do struggle to meet basic needs or absorb short-term shocks. One review cited data showing that in 2019, 3 in 10 adults had difficulty meeting financial needs, and about 37% reported difficulty coping with short-term liquidity needs. In that environment, caution is understandable. The issue is when caution becomes the default setting for every decision, even the ones that are not actually emergencies.
The household can quietly adapt around one person’s worry
Financial worry does not stay inside one person’s head. It changes the tone of the household. Partners may start asking fewer questions because they do not want to trigger stress. Children may learn that some requests are safer than others. The family slowly adapts to the father’s internal alarm system.
That adaptation can be subtle. The family may become very good at avoiding unnecessary spending while missing the chance to talk openly about priorities. Or a partner may sense the anxiety but not know whether it is about actual cash flow, old debt, future college costs, retirement, or something less tangible like feeling replaceable.
The result is often a household that appears financially disciplined but is not fully discussing the emotional meaning of money. That matters because unspoken worry tends to reappear in arguments over relatively small issues. The fight is rarely about the specific receipt. It is usually about the fear underneath it.
A better way to sort real risk from imagined risk
The most useful response to this pattern is not “stop worrying.” Fathers usually need a way to separate actual financial exposure from the emotional story attached to it. A simple three-question check can help.
First: Is this decision about a true shortage, or about the fear of a future shortage? If the bill cannot be paid without harm, the decision is real and immediate. If the concern is more abstract, the issue may be emotional load rather than cash flow.
Second: What is the downside if this goes wrong, and how likely is that downside? A lot of money worry comes from treating every downside as equally probable. Writing the specific risk down often shrinks it.
Third: Does this choice protect the family, or just protect my feeling of control? Those are not always the same thing. Sometimes control is useful. Sometimes it is simply a way to avoid the discomfort of making a balanced decision.
This is where personalized advice matters. The best financial guidance is not copied from people with a totally different life situation. It has to fit the actual household, because what looks prudent in one family can be unnecessarily restrictive in another.
What helps fathers make calmer money decisions
Calmer decisions usually come from making money less atmospheric and more concrete. If a father can turn vague dread into a few visible numbers, he can often think more clearly.
A few practical moves help:
– Separate fixed obligations from flexible spending so the month feels legible.
– Name the specific fear before making the decision: job loss, debt, unexpected repairs, retirement, college costs, or something else.
– Decide in advance which purchases are allowed to be emotional, not just efficient. Families need ease and recovery, not only survival.
– If a decision is large, pause long enough to compare the short-term cost with the long-term effect on stability.
– When in doubt, discuss the trade-off with a partner in terms of priorities, not blame.
The goal is not to become carefree. It is to stop letting unspoken fear make every decision for you. Many fathers are already doing the invisible work of trying to keep the household safe. The next step is making sure that effort leads to clarity, not constant strain.
When the worry is bigger than the budget
Sometimes financial worry is not mainly about the current budget at all. It may be tied to debt, underemployment, past instability, or a long stretch of carrying responsibility without relief. HelpGuide notes that people struggling with debt are more than twice as likely to suffer from depression, and financial stress can also trigger anxiety symptoms, including panic-like physical reactions. That does not mean every worried father is experiencing a mental health crisis. It does mean that persistent money fear deserves attention, especially when it starts affecting sleep, concentration, relationships, or decision-making.
It is also worth remembering that stress can mask itself as productivity. A father may look functional while privately feeling exhausted by the need to anticipate everything. If the same money questions keep replaying, or if every expense feels loaded with dread, the issue may no longer be the purchase itself. It may be the amount of emotional labor attached to being responsible for everyone else’s security.
That is the real pattern behind quiet financial worry: not recklessness, but constant internal monitoring. Once you can see that pattern, it becomes easier to respond to the actual problem instead of treating every decision like a test.
Related Reading
- Father Financial Worry: Why It Shapes Every Choice
- Why Men Over 40 Quietly Worry About Inflation
- Why Fathers Quietly Feel Financially Unappreciated
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.