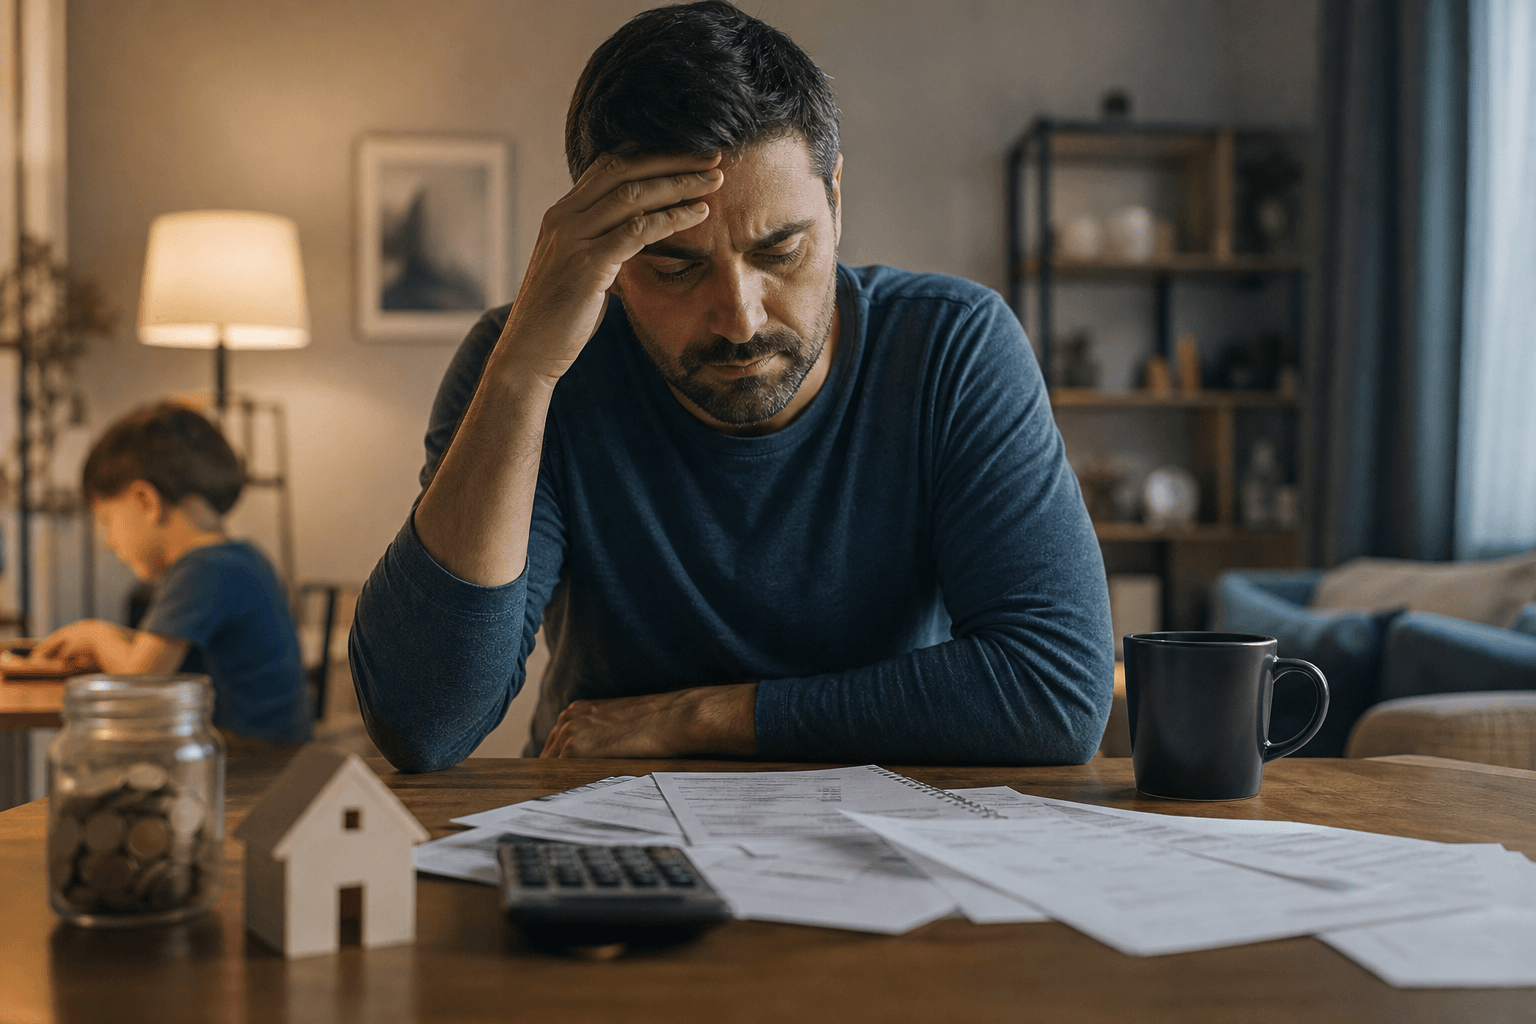
A lot of fathers do not feel financially stressed only when money is scarce. They feel it in the years when income is steady, bills are paid, and life looks normal from the outside. The pressure is quieter than panic, but it can be constant: keeping up with housing costs, childcare, school expenses, savings goals, and the expectation that a father should stay composed while carrying it all. That mix of responsibility and silence is often what makes the strain hard to name.
The pressure is often about responsibility, not just income
Financial pressure in fatherhood is not always a math problem. Often, it is a role problem. Many fathers absorb a steady expectation that they should provide, protect, and keep the household stable, even when their income has not changed much.
That means the stress can exist during objectively good times. A promotion, a stable job, or a paid-off debt does not necessarily make the pressure disappear. Instead, the pressure shifts into a different form: less fear of immediate crisis, more fear of falling short of what the family needs next.
That is why the feeling can be so hard to explain. On paper, things may look fine. In private, a father may still be running a constant internal calculation about whether he is keeping up.
Stable pay does not erase the feeling of being one setback away
A useful way to understand this is to separate income stability from emotional security. A steady paycheck helps, but it does not fully protect someone from money stress. Financial stress can come from unexpected difficulties, weak planning, or simply the sense that there is not enough room for error.
That is especially true for fathers who see themselves as the financial anchor in the family. When that identity is strong, even ordinary expenses can start to feel loaded. Childcare, school costs, transportation, medical bills, and housing are not just line items. They become evidence of whether the system is holding.
This is one reason many fathers stay quiet about money pressure. If the family is not in a visible crisis, the stress can feel illegitimate, almost embarrassing to name. But quiet pressure is still pressure. It often shows up as vigilance: checking balances more often, hesitating before spending, or mentally rehearsing worst-case scenarios.
Family growth changes what “enough” feels like
Fatherhood tends to expand the definition of what money has to do. Before children, money may mostly cover lifestyle and personal stability. After children, it must cover uncertainty, care, development, and future planning all at once.
That expansion matters because the target keeps moving. A father may have reached a level of income that once felt comfortable, only to find that the family’s needs have grown faster than his sense of comfort. New school fees, larger housing needs, activities, travel, and long-term savings can make a previously manageable budget feel tight.
In behavioral terms, this creates a moving reference point. The family is doing well, but the mind keeps updating the standard. What once felt like enough now feels merely adequate. And “adequate” is not a particularly relaxing place to live when you feel responsible for everyone else’s margin of safety.
The pressure stays quiet because many fathers are taught to carry it alone
Many fathers are not only managing money; they are managing how money talk is supposed to sound. They may feel they should stay calm, avoid complaints, and not burden a partner or children with worry. That can make the stress feel invisible even inside the home.
Silence can also become a habit. If a man learned early that financial concerns should be handled privately, he may not notice how much energy he spends containing them. He might appear steady while mentally tracking every upcoming expense, every possible disruption, and every decision that could make him look less capable.
The problem with quiet pressure is that it is easy to misread. Other people may see a reliable provider. He may feel like someone who is constantly one decision away from failing the role. Those two realities can exist at the same time.
A simple check: is the stress about cash flow, identity, or both?
When money feels heavy during good times, it helps to identify what kind of pressure is actually present. A quick self-check can clarify that.
Ask three questions:
– Is this mainly about current cash flow, meaning the budget really is tight?
– Is it about future uncertainty, meaning I fear what one setback would do?
– Is it about identity, meaning I feel I am supposed to handle this without strain?
Often the answer is some mix of all three. But separating them matters, because each one calls for a different response. Cash flow problems need budget changes. Future uncertainty may need a larger buffer or clearer plan. Identity pressure may need a different way of talking about money at home.
This small diagnosis can be surprisingly useful. It keeps every uneasy feeling from being treated as proof that the household is failing.
The pattern that makes “good times” feel fragile
The strange thing about financial pressure in good times is that stability can make it more visible, not less. Once the basics are covered, attention moves to what is not covered yet: savings, retirement, a bigger emergency fund, college costs, home repairs, and the unknowns that sit just beyond the current budget.
That is why some fathers feel most pressured not during disaster, but during responsibility. They are no longer focused on surviving the month. They are focused on trying to secure the next five years, or the next 15.
This is also where comparison can quietly amplify stress. A father may not be comparing himself to luxury or excess. He may be comparing himself to a standard of steadiness that seems to come naturally to other people. That comparison can make ordinary concerns feel personal, even when they are common.
What helps more than telling yourself to relax
For this kind of pressure, reassurance alone usually is not enough. The mind wants evidence, structure, and a sense of control.
A few practical moves can help:
– Put the family’s monthly fixed costs in one place, so the core burden is visible.
– Separate essential expenses from flexible ones, so every dollar does not feel equally urgent.
– Decide what amount of short-term cushion would make the household feel safer.
– Have one honest money conversation with a partner or trusted person instead of carrying the whole picture privately.
The goal is not to eliminate responsibility. The goal is to make responsibility legible. When the financial picture is clear, the mind usually stops treating every expense like a possible emergency.
If the pressure is tied to debt, that can add a different layer. Research from help and stress resources notes that people struggling with debt are more likely to experience depression, and debt-related stress can also intensify anxiety. That does not mean every father with debt is in crisis. It does mean debt can turn ordinary financial vigilance into something heavier and harder to switch off.
A steadier way to define success at home
For many fathers, the deepest shift is not a budgeting trick. It is redefining what financial competence looks like. It is easy to assume that a competent provider should feel calm all the time. In practice, competence often looks more ordinary: knowing the numbers, naming the pressure, and making adjustments before stress turns into silence.
That reframe matters because fathers can otherwise mistake constant worry for proof that they are failing. In reality, worry may simply be the mental cost of caring about a family and knowing how much depends on a handful of decisions.
A better question than “Why am I stressed if things are okay?” is “What exactly am I trying to protect?” Once that answer is clear, the pressure becomes easier to organize. And when money pressure is organized, it usually becomes a little less lonely too.
Related Reading
- Why Fathers Quietly Feel Pressure to Never Slow Down
- Why Fathers Quietly Feel Financially Unappreciated
- Why Working Fathers Feel Like Financial Rest Never Comes
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.