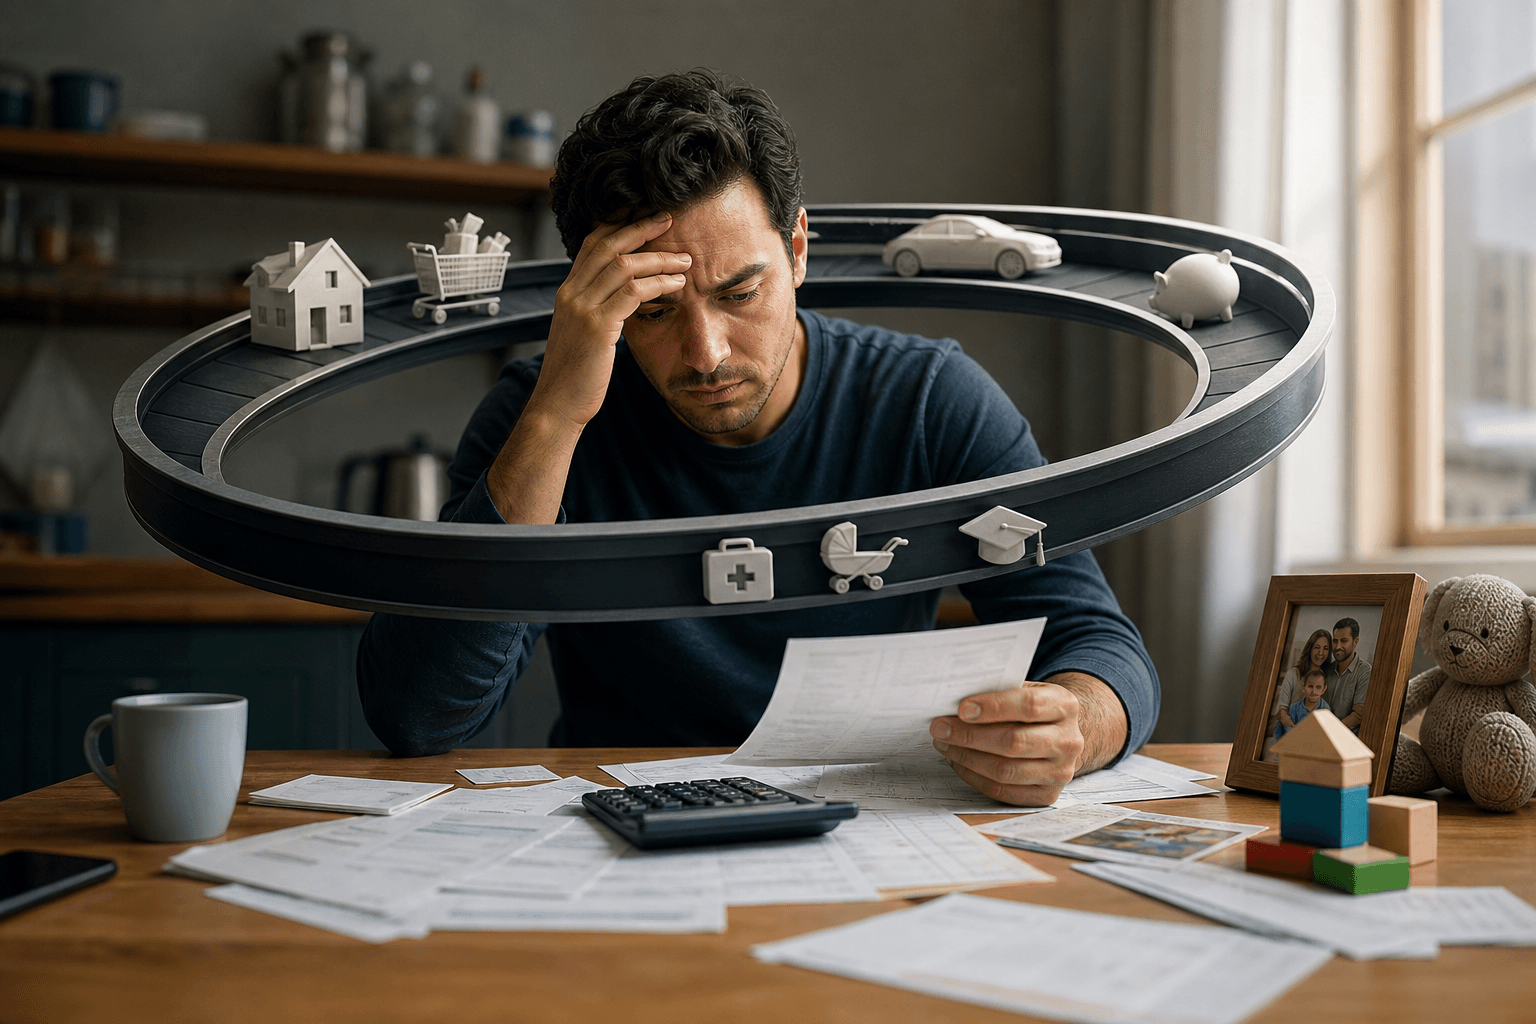
For people who support others, money pressure often feels less like a problem to solve and more like a state that never fully turns off. Bills may be paid, but the mental load stays active: children, partners, parents, employees, clients, or a household all keep the budget feeling exposed. That constant vigilance is exhausting. The pattern is not just about having “enough” money; it is about how responsibility changes the way every dollar is experienced.
When your money has to cover more than your own life
Financial pressure feels different when other people depend on your decisions. A provider is rarely only managing personal spending. They are carrying rent, groceries, childcare, transportation, school costs, medical bills, and the small emergencies that never arrive at a convenient time.
That changes the emotional math. Even if the budget is technically balanced, there is usually no sense of being done. Every category feels connected to someone else’s stability, so one problem can seem to threaten the whole system. The result is a kind of always-on alertness that makes money feel unfinished, even in a decent month.
Scarcity feels louder when the stakes are relational
Money is not just a spreadsheet problem. It is tied to the basic drive to survive, and when that drive feels blocked, stress intensifies. For providers, the pressure is amplified because the threat is rarely personal alone. It is also relational: a shortfall can mean missed opportunities, a disrupted routine, or an uncomfortable conversation with someone who depends on you.
That is one reason financial stress can feel endless. A provider may not experience the question as “Can I afford this?” but as “What happens to everyone if I cannot?” That broader question has no clean endpoint. Even when today’s bill is handled, the next decision is already waiting.
The mental load keeps the problem open
One of the hardest parts of provider stress is that it lives in the background. The mind keeps running silent checks: Is the account low? Did the payment clear? What if the car needs repairs? What if income drops next month? This constant monitoring can become its own form of fatigue.
Vanderbilt University notes that not feeling knowledgeable or confident about managing money can feed financial stress, and that seeking advice can help people take inventory, make a budget, and monitor progress. That point matters because uncertainty often stretches the feeling of pressure. When there is no clear plan, money problems can feel emotionally bigger than their actual balance-sheet size.
Providers are especially vulnerable to this because they tend to think in contingencies. They are not only paying today’s bills; they are trying to prevent tomorrow’s crisis. That habit is responsible and often necessary, but it can also keep the nervous system from ever fully standing down.
Responsibility turns every expense into a decision about safety
For a provider, spending is rarely simple consumption. It is often interpreted as a tradeoff between present comfort and future security. A haircut, a birthday gift, a school trip, a home repair, or a night out can all trigger the same underlying question: Is this reasonable, or am I risking the margin everyone relies on?
That is why financial pressure can persist even when income improves. More money does not automatically reduce stress if the role of provider expands faster than the financial cushion. New obligations arrive quickly, and old obligations rarely disappear. The budget may grow, but so does the list of people and priorities it must serve.
This creates a strange pattern: the more responsible someone is, the less relief they may feel. They notice problems earlier, plan more carefully, and absorb more uncertainty. Those are useful traits, but they also mean the pressure stays visible instead of fading into the background.
Why relief is brief and worry returns fast
Financial pressure often feels endless because each solved problem exposes the next one. A utility bill gets paid, then groceries go up. A debt payment is made, then childcare costs more. A side income helps, then a new expense appears. The provider is left with the sense that there is always another corner of the budget waiting to break.
This is not necessarily irrational. Life does contain recurring costs and occasional shocks. But the mind does not experience them as separate events. It experiences them as a continuous test of adequacy. If there is no buffer, every new expense can reactivate the same stress response.
That is why even “good months” may not feel good. When the gap between income and obligations is narrow, relief does not last long enough to settle in. The brain registers fragility more quickly than it registers stability.
What makes provider stress worse than ordinary budgeting pressure
Provider stress usually combines several forces at once. Income may be variable. Responsibilities may be shared unevenly. Debt may already be present. Savings may be thin. And there may be little room to reduce expenses without affecting someone else’s well-being.
The combination matters more than any one factor. A person can tolerate a tight budget if it is predictable and temporary. But when the budget must absorb multiple roles at once, pressure becomes structural. That is what makes it feel endless: it is not one problem with one solution. It is a recurring negotiation between limited resources and ongoing obligations.
This is also why shame often makes the feeling worse. Providers may think they should be calmer, more prepared, or more in control than they feel. That self-criticism adds a second layer of stress on top of the financial one.
A better way to measure whether pressure is actually easing
When money feels endless, the usual question—“Am I doing enough?”—is too vague to help. A more useful question is: “Is the system becoming more resilient?”
Here is a simple check:
– Can I name the next three obligations without guessing?
– Do I know which expenses are fixed, flexible, and optional?
– Is there even a small buffer for one unexpected cost?
– Have I reduced one source of uncertainty in the last month?
– Do I have a clearer plan than I did three months ago?
If the answer to even one of those is yes, pressure may still be present, but it is not identical to hopelessness. Providers often need evidence of control, not perfection. Progress is easier to feel when it is specific.
Another useful signal is whether the budget is making decisions faster. If every purchase requires a new emotional debate, the system is too fragile. If a few categories are clearly defined, money starts to feel less like a daily emergency and more like a managed set of priorities.
What helps providers interrupt the loop
The goal is not to eliminate responsibility. It is to make responsibility less psychologically expensive.
Start by giving the money a shape. List the non-negotiables first: housing, food, utilities, transportation, debt minimums, childcare, and any obligations you cannot ignore. Then separate the costs that are important but adjustable. This turns vague dread into visible structure.
Next, identify the one risk that keeps repeating. Is it cash flow timing? A forgotten annual expense? Emergency repairs? Variable income? Provider stress often comes from the same few pressure points showing up again and again. Reducing one of them can make the whole budget feel less hostile.
It also helps to get outside perspective. Vanderbilt’s guidance emphasizes seeking financial advice because a lack of confidence can feed stress. That does not mean everyone needs formal wealth management. It means many people benefit from a second set of eyes, whether from a financial adviser, a coach, or reliable educational resources. Sometimes the burden feels endless because no one has helped translate it into a workable plan.
Finally, remember that a provider does not need to feel secure to begin building security. A small buffer, a clearer budget, and one recurring cost brought under control can change the emotional texture of money faster than people expect. The feeling may not disappear overnight, but it can stop feeling like a permanent emergency.
Related Reading
- Why Financial Stress Feels Constant for Family Providers
- Why Financial Security Feels Further Away for Working Men
- Why Financial Pressure Feels Worse With Age
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.