Some men spend years working, earning, budgeting, and solving money problems, yet still feel one mistake away from falling behind. That feeling is not always about the numbers on a spreadsheet. It often comes from pressure, shame, comparison, and the habit of treating financial competence as a test of worth. In daily life, that can make experienced men appear steady while privately feeling uncertain, guarded, or “not enough.” Understanding that gap matters, because the feeling itself can shape spending, secrecy, risk-taking, and stress.
When experience and confidence stop lining up
Financial experience usually brings skills: you learn how paychecks work, how to spot a bad deal, and how to avoid the most obvious mistakes. But experience does not automatically produce a steady sense of safety. A person can know what to do with money and still feel exposed if the emotional meaning of money never changed.
That disconnect matters because money is never just arithmetic. It is also a signal about status, stability, competence, and control. If a man has been taught, directly or indirectly, that being “good with money” is part of being a responsible adult or a dependable partner, then even a temporary setback can feel like a personal failure rather than a normal financial event.
That is one reason financial insecurity can linger after years of experience. The skill may be real, but so is the fear that one disruption could expose everything.
The provider role still shapes the way many men judge themselves
A persistent theme in the research is the internalized pressure to provide. Even as household roles have changed, many men still carry the idea that their value is tied to financial success. Psychology Today notes that the expectation to “have it all together” financially has not disappeared, and when men do not meet that standard, shame often follows.
That shame changes the way money problems are experienced. Instead of thinking, “I need a plan,” a man may think, “I’m falling short.” Instead of discussing a cash-flow problem early, he may wait and try to fix it privately. The issue is not just the debt, the bill, or the shortfall; it is the fear of what that shortfall seems to say about him.
BetterHelp reports that 7 out of 10 adults believe men should be the breadwinners in their families. Whether or not a household actually operates that way, the belief itself can become a quiet background pressure. A man may earn a decent income and still feel as if he is underperforming because the standard in his head is not “stable life,” but “unquestionable provider.”
Shame turns ordinary money problems into private ones
Once shame enters the picture, people tend to hide. That is where financial insecurity becomes more than a feeling; it becomes a pattern. Psychology Today notes that men are more likely than women to commit financial infidelity, hiding debts, purchases, or financial decisions from their partners.
This secrecy is understandable, but it is costly. Hiding a problem usually makes it harder to solve, and it also keeps the body in a state of constant tension. A man who is worried about being judged may keep mental tabs on every bill, every purchase, and every pending expense without ever letting the concern become a shared plan.
Over time, that private vigilance can make someone feel even less secure. He is carrying the problem alone, which means there is no outside reality check to say, “This is manageable,” or, “We need to adjust, but we are not in crisis.” The hidden problem grows larger in the mind than it may be in the bank account.
Stress does not always look like panic; sometimes it looks like risk
Men also do not always respond to money stress by slowing down. BetterHelp notes that men may be less likely to manage stress or notice stress-related symptoms, and more likely to take risks when under high stress. That matters because financial insecurity can push people toward exactly the behaviors that make them feel more insecure later.
For example, someone might:
– keep spending to maintain a sense of normalcy
– delay checking accounts or bills
– make a bigger purchase to feel in control
– take on extra risk to “catch up” faster
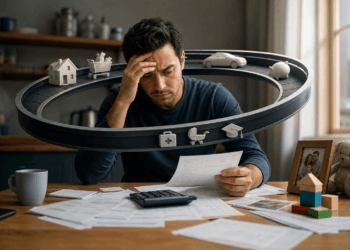
These moves can make emotional sense in the moment. If money feels tight, a person may want relief, not another lecture. But risk can become a way of avoiding the slow, uncomfortable work of facing reality. The result is often a cycle: uncertainty creates stress, stress creates avoidance or risk, and the outcome deepens uncertainty.
Financial insecurity can come from the story, not just the balance
A man may look financially fine from the outside and still feel behind because his reference point is not his actual situation. It is the story he tells himself about where he should be by now. That is where money dysmorphia becomes useful as a concept: it describes a distorted perception of one’s financial situation, where someone may feel unsafe or like a failure even when reality is more stable than the feeling suggests.
This does not mean the feeling is fake. It means the feeling and the facts are not always aligned. A person can have savings, a solid income, and manageable debt while still believing he is one missed paycheck away from collapse. That belief may come from earlier scarcity, a bad financial period, family expectations, or years of comparing himself with people who appear more successful.
The practical takeaway is simple: if your money anxiety feels bigger than your actual risks, the problem may not only be the budget. It may also be the way you are interpreting your position.
A quick way to separate real risk from emotional noise
One useful check is to ask three questions:
1. What is the actual problem right now?
2. What am I afraid this problem means about me?
3. What would I advise a friend to do in the same situation?
This simple separation can reveal whether you are dealing with a true cash-flow issue or a self-worth issue dressed up as a cash-flow issue. If the answer to question one is “I need a better plan,” that is one kind of problem. If the answer is “I feel like a failure because I had to use savings,” that is another.
The third question is especially helpful because people are often far kinder and more realistic with other adults than they are with themselves. A friend’s temporary setback usually looks solvable. Your own may look like evidence.
What a steadier response to money looks like in daily life
A more stable response does not require perfect confidence. It requires reducing the amount of secrecy and self-judgment attached to ordinary money work. That often starts with a few practical habits.
First, make the numbers visible. If money anxiety thrives on ambiguity, then regular review is a form of relief. Knowing your balances, due dates, and monthly obligations will not erase pressure, but it can replace vague dread with specific action.
Second, talk earlier than feels comfortable. Men who have been taught to solve problems alone often wait too long to ask for help or even to mention a concern. But sharing a money issue early can prevent the shame from hardening into secrecy.
Third, separate performance from worth. A poor financial month does not prove that you are irresponsible, weak, or failing at adulthood. It usually means a plan needs revision.
Fourth, beware of stress spending and stress risk. If you notice yourself wanting to buy, gamble, speculate, or otherwise force a quick emotional reset, pause long enough to name what you are actually trying to relieve.
The real goal: competence without self-punishment
Many men do not need more lectures about discipline. They need a way to stay financially engaged without turning every mistake into an identity crisis. That is the deeper issue behind feeling financially insecure despite experience: the money skill may exist, but the emotional model still says safety is fragile and mistakes are humiliating.
The research points to a clear pattern. Provider pressure creates shame. Shame encourages secrecy. Secrecy prevents reality checks. Stress can then trigger avoidance or risk-taking, which makes insecurity feel even more justified. That loop can run for years unless someone breaks it with honesty, visibility, and a less punishing definition of competence.
Experience should make money decisions easier, not heavier. If your experience has not produced confidence, it may be because the problem is not knowledge alone. It is the story you are carrying about what money is supposed to prove.
Related Reading
- Why Many Men Feel Financially Insecure Despite Experience
- Financial Exhaustion: Why Many Men Feel It Now
- Why Men Over 50 Feel Financially Uncertain About the Future
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.