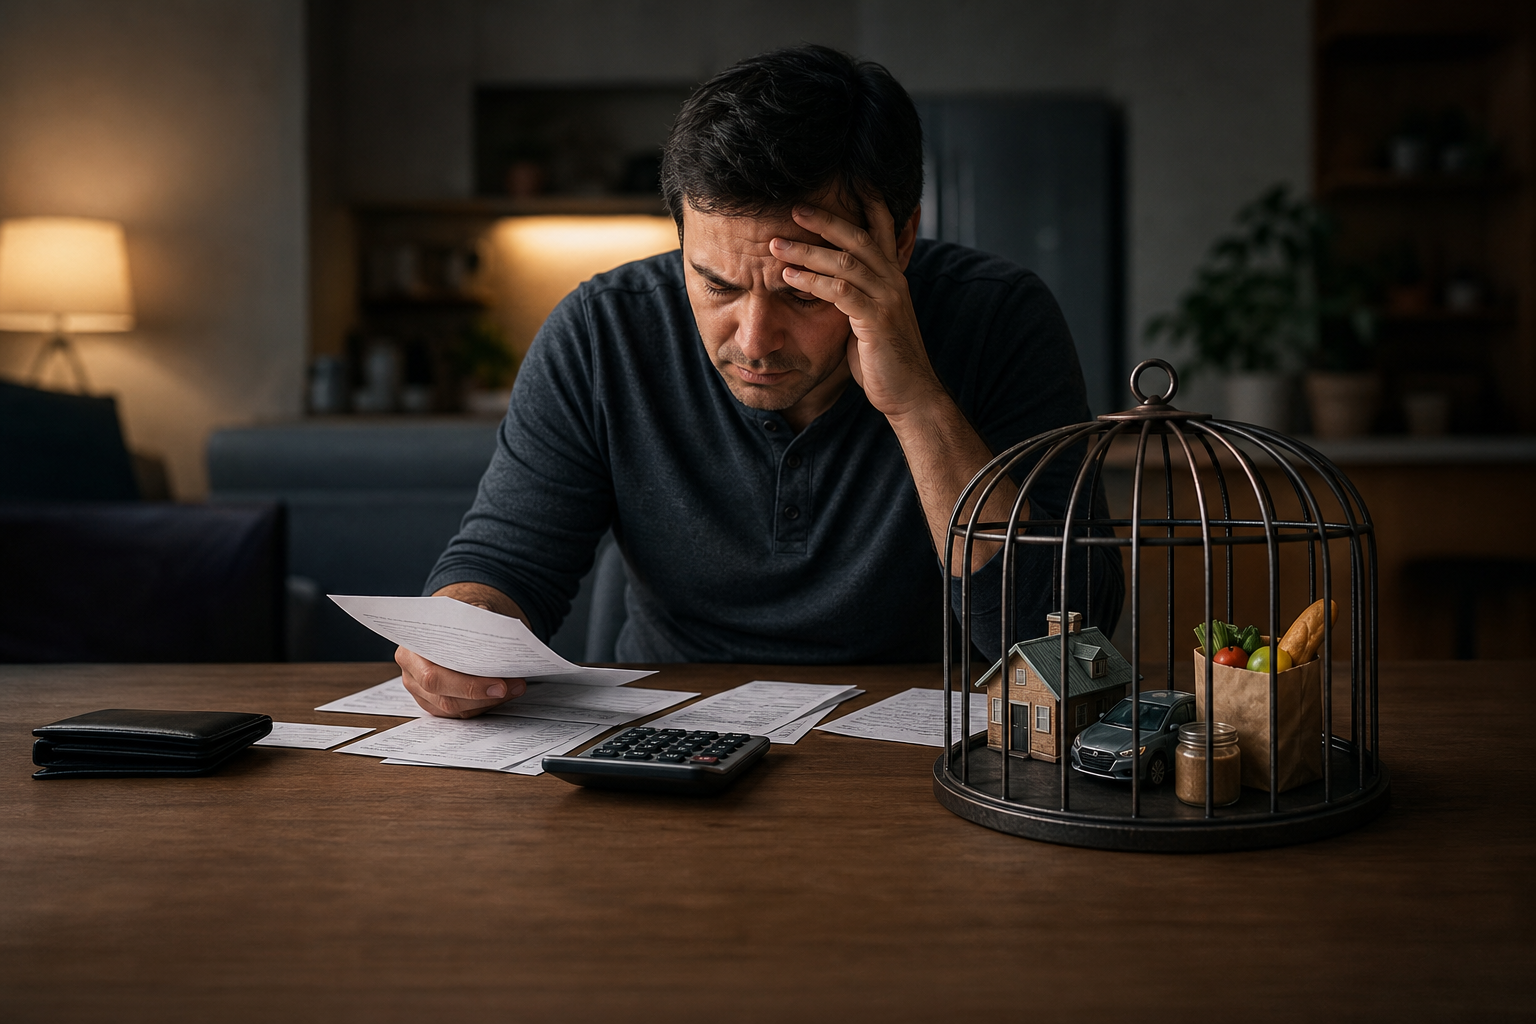
For many working men, the strain is not just that prices are high. It is that the normal monthly math no longer feels workable. A paycheck arrives, bills claim most of it, and any gap is so small that one surprise expense can wipe out the rest. That creates a specific kind of pressure: not only financial stress, but the feeling that effort is no longer converting into progress. Once that pattern repeats, the cost of living can start to feel less like an inconvenience and more like a locked door.
When the paycheck disappears before the month does
A lot of working men describe the same basic experience: they are employed, they are trying, and still there is no sense of breathing room. The problem is rarely a single bad choice. More often, the monthly income is already spoken for before the month really starts. Rent or mortgage, utilities, transportation, food, child care, debt payments, and insurance can absorb nearly everything left after taxes.
That is why the feeling of being “trapped” can be so strong. If there is no surplus, then there is no margin. And when there is no margin, ordinary life begins to feel fragile. A car repair, a school fee, a medical copay, or even a higher grocery bill can force the next decision into debt, delay, or cutting something essential.
This is not just a personal impression. In the UK, poverty statistics show the scale of the squeeze: in 2021/22, 17% of individuals were in poverty before housing costs, rising to 22% after housing costs. That gap matters because housing often determines whether a working household feels stable or stretched to the edge.
Why being employed does not always feel like getting ahead
Employment used to carry a simple promise: work hard, stay steady, and life becomes more manageable. But when wages lag behind the cost of everyday life, the promise breaks down. A man can do everything “right” by traditional standards and still feel like he is losing ground.
That mismatch matters emotionally because work is not just a source of money. For many men, it is also tied to identity, responsibility, and self-respect. If the paycheck cannot cover rising bills with any comfort, the result is often shame, frustration, or a sense that effort is being wasted. The problem is not laziness. It is that the reward system no longer matches the effort system.
This is one reason financial stress can feel especially personal for men who were raised to see income as proof of reliability. A working man may not say, “I cannot afford this,” even when that is objectively true. Instead, he may keep pushing, borrowing from the future, or absorbing stress silently because admitting strain feels like admitting failure.
The bills that do the most damage are usually the recurring ones
The strongest pressure usually does not come from one giant expense. It comes from the bills that repeat and rise quietly. Rent, groceries, gas, child care, minimum debt payments, and insurance create a base level of spending that can be hard to reduce without changing where and how you live.
That matters because fixed or semi-fixed costs leave little room for recovery. If income goes up a little but housing, transportation, and food go up too, the extra money may never be felt. It gets absorbed before it reaches savings or flexibility. In practice, this creates a treadmill effect: more work, same strain.
The Cost of Living crisis also pushes people toward short-term financing just to cover normal life. A survey from the Center for American Progress found that more than one-third of Americans, 35%, were late paying a bill in the past year, and the rate was higher among working-class Americans at 42% compared with 23% of college-educated people. The same research noted that high prices have pushed more people toward “Buy Now, Pay Later” and payday loans, sometimes for everyday essentials such as groceries, rent, and child care. That is a sign that the gap is not only emotional; it is structural.
Why debt makes the trap feel deeper
Once debt enters the picture, the cost of living can feel heavier even if spending does not change. Debt payments reduce the amount of each paycheck that is actually available for living. Then the remaining money has to cover the same expensive basics, which means the margin gets even thinner.
This is how people end up feeling stuck in a cycle:
1. Income covers most, but not all, monthly costs.
2. A surprise expense appears.
3. Debt, late fees, or borrowed money fill the gap.
4. Monthly obligations rise.
5. The next paycheck has even less room.
That cycle is exhausting because it removes choice. A man may feel that every paycheck is already committed to the past, with nothing left to build a future. In that situation, it is easy to interpret the problem as a personal failure. But often the real issue is that the household is trying to function without any financial cushion at all.
The burden can become especially visible in relationships, where one partner may experience the strain as unreliability, while the other experiences it as constant pressure. That mismatch can create resentment fast. Money conflict is often not about the arithmetic alone; it is about the repeated feeling that there is never enough room to make a clean decision.
The emotional script many men are still expected to follow
A lot of men are taught, directly or indirectly, that they are supposed to absorb financial pressure without complaining. They are expected to keep working, stay calm, and present confidence even when they are worried. That script can make the cost of living feel even more oppressive, because it turns a money problem into a private burden.
The result is a double bind. If a man speaks openly about being squeezed, he may worry that he sounds weak. If he stays quiet, the stress has nowhere to go. Either way, the pressure remains.
The research on men’s financial stress points to this disconnect clearly. One survey summary said men are privately rejecting the idea that they should be defined by income and want meaningful lives, strong relationships, and a sense of purpose instead. That helps explain why money strain can feel so demoralizing: the issue is not only that life is expensive, but that many men feel they are failing a role they never fully chose.
A simple way to tell whether you are dealing with prices, habits, or both
If the cost of living feels crushing, it helps to separate three different problems that often get blurred together.
**1. A price problem** means the basics themselves are too expensive relative to income. Rent, food, and transportation consume too much of the paycheck.
**2. A cash-flow problem** means the money may technically be enough over a month, but it does not arrive in a useful pattern. Bills hit before paydays, or irregular expenses break the budget.
**3. A behavior problem** means some spending, borrowing, or bill management pattern is making the squeeze worse than it needs to be.
Most people are dealing with some combination of all three. The point of the distinction is not blame. It is clarity. If the issue is mostly pricing, then cutting small expenses will not solve it. If the issue is cash flow, then timing matters as much as totals. If the issue is behavior, then one or two changes can create meaningful room.
A useful question is this: if your income stayed the same for six months, what exact bill or behavior would need to change first to stop the pressure from building? That question often reveals whether the problem is an income gap, a timing problem, or a spending pattern that has become automatic.
A steadier response starts with making the pressure visible
The goal is not to “think positive” about a hard situation. It is to make the pressure legible enough that you can act on it. When money feels vague, it feels bigger than it is. When you can name where the squeeze actually happens, the problem becomes more workable.
A practical first pass might look like this:
– List the bills that recur every month.
– Mark which ones are fixed, variable, or easy to pause.
– Compare those to the exact timing of your paychecks.
– Identify the one expense that most often forces you to borrow, delay, or use credit.
That last item is important. The expense that creates the most stress is not always the largest expense. It is the one that breaks the system. For some households, that might be fuel or commuting costs. For others, it is food, child care, or a debt payment that is too large to absorb comfortably.
Once that weak point is visible, the response becomes more specific. Sometimes it means changing a due date. Sometimes it means lowering one recurring bill. Sometimes it means planning around a known shortage instead of pretending the shortage is random.
The real relief comes from replacing helplessness with a plan
What makes the cost of living feel trapping is not just high prices. It is the combination of high prices, low margin, and no clear route to improvement. Working men often feel that combination intensely because it collides with expectations about stability, provision, and self-control.
But the moment you can identify which part of the squeeze is doing the damage, the situation changes shape. A price problem can be compared. A cash-flow problem can be timed. A behavior problem can be adjusted. Even if none of those fixes is immediate, naming the actual mechanism is better than carrying the whole situation as one vague failure.
That is the first real step out of the trap: not pretending the pressure is imaginary, and not treating it as proof of personal inadequacy either. It is a money system problem, and money system problems become easier to manage when they are broken into parts.
Related Reading
- Why Men Feel Trapped by Lifestyle Costs
- Why Working Men Feel Like Their Savings Never Grow
- Why Men Over 50 Feel Financially Uncertain About the Future
Keep Exploring the Pattern
Watch more breakdowns of real-life money behavior on our YouTube channel.
Browse the full Money Behavior Library to explore more patterns like this one.
If you want a clearer view of your monthly patterns, try the Salary Breakdown Calculator, the Subscription Cost Calculator, or the Bill Due Date Planner.
Explore more patterns in the Money Behavior Library — a growing collection of real-life financial patterns explained clearly.
Disclaimer:
This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making personal financial decisions.